But how do activist actions affect another important but lower-profile stakeholder group: debtholders, or the lenders or bondholders with a stake in the targeted company?
That question led Wan Wongsunwai, an assistant professor of accounting information and management at the Kellogg School, along with collaborators Jayanthi Sunder and Shyam Sunder of the University of Arizona, to study the effects of activists on debtholders. Specifically, the researchers investigated how different types of activism impacted the lending terms offered to the companies being targeted.
They found that activist shareholders could both harm or help debtholders, depending on the activists’ objective. While attempts to shift value from the company to the shareholders had negative consequences for debtholders, other actions, such as efforts to block ill-advised mergers, were a benefit.
Who Is Affected by Activist Activity?
Hedge-fund activist shareholders have become controversial celebrities in the business world, waging highly publicized battles over the governance of the companies in which they invest. Pershing Square Capital Management, led by activist Bill Ackman, for example, has tangled with the likes of Target, JC Penney, and Herbalife in recent years, with mixed results for the broader shareholder pool.
“Activist hedge funds have become increasingly aggressive and sophisticated,” Wongsunwai says. “What we thought of as ‘corporate raiders’ in the past used to buy companies outright to change them, but activists can achieve change with a much smaller stake. It’s more about sophistication than size of share.”
Many see activists as attempting to shift a portion of company value from other parties—such as management—to themselves. Other shareholders, including individuals holding stock in a target company, might profit from activist intervention, or might not, depending on changes in the stock price. “The shareholders will benefit if activists create economic value,” Wongsunwai says.
But what about debtholders? “Debtholders are sort of locked in,” Wongsunwai says. “They make an investment [through a bond or loan] in a company, then typically remain hands-off. So we can think of them as ‘bystanders’ who may benefit or suffer from activism.”
To illuminate the effects of activism on debtholders, Wongsunwai and colleagues designed a research study. “We wanted to understand to what extent value is shifting from debtholders—who have no say in management issues—to activists, who have a lot of power,” he says.
Not All Bad—or Good
The researchers looked at lending terms before and after hedge-fund interventions at 797 firms between 1995 and 2009—including shifts in interest rates and protective mechanisms lenders put into place through loan or credit-related covenants. “These are like ‘dials’ lenders and borrowers can use to negotiate,” Wongsunwai says.
They found that activism had a range of effects for debtholders. Overall, post-activism interest rates rose by 30 basis points, on average. Lending terms were also more restrictive.
While that meant more interest paid to debtholders, it also suggested a higher likelihood of negative consequences, such as payment delays or defaults. “Default rates are not insignificant,” Wongsunwai says. “Banks care about this.” In short, activism was seen as driving higher risk for debtholders.
Similarly, when activists successfully demanded greater dividends or otherwise shifted more of the company’s value to themselves, it had a naturally negative effect on debtholders. Debtholders were also worse off when activists tried to force the company in question to be acquired. “Lenders like certainty,” Wongsunwai says. “They don’t want things to change. A merger or acquisition disrupts a contract from a lender’s point of view.”
“But debtholders don’t always lose,” he says. “It really depends on what the activist is trying to do.”
In some cases, debtholders benefited from activist events. For instance, targeting an entrenched CEO served debtholders’ interests, as reflected in an average interest rate decrease of 27 basis points. “If activists can stop a CEO from gnawing away at company resources, then debtholders will gain from that,” Wongsunwai says. Activists also drove benefits for debtholders when they blocked mergers that were seen as unwarranted or part of “empire-building,” rather than value-creating moves with a solid business case.
The Size of the Pie, the Size of the Slices
So how does this research inform our broader understanding of the value that activist shareholders bring to the table?
“It’s tricky,” Wongsunwai says. “You can argue that activists bring discipline because managers want to avoid being targeted. But you can also see them as opportunistic and exploiting weak companies.” There is growing support for the view of activists as discipliners, he says, but this role can be difficult to prove or quantify.
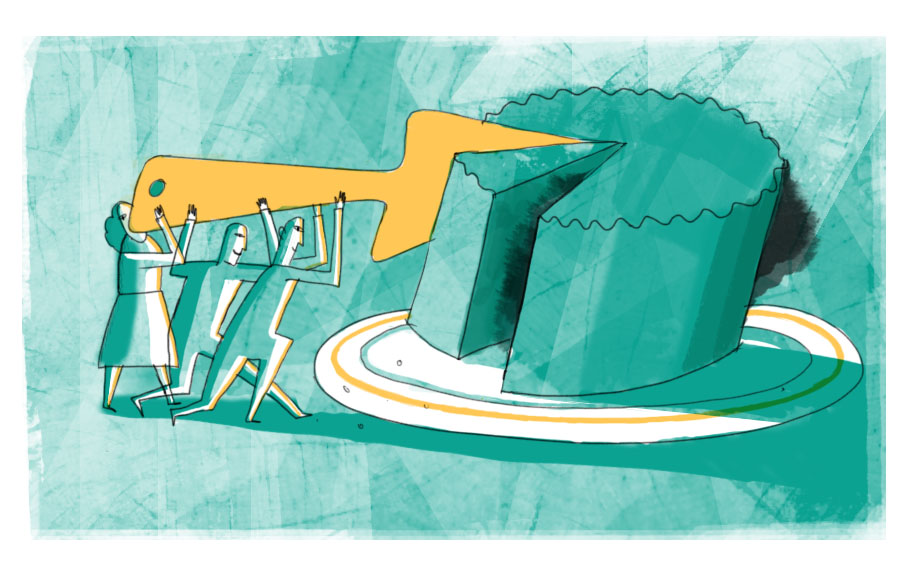
“Overall it’s about the size of the pie and the individual pieces,” Wongsunwai says. “Does the total value of the firm go up as a result of activist actions, and how much do the pieces held by each group, including the debtholders, grow or shrink?”
In the future, Wongsunwai may shift his attention to a different kind of activism: the political variety. “There are more connections now between corporations and politicians, and it’s important to understand what that means for markets and society,” he says.